
The short answer
No. The exchange survives an unfinished building, but you get credit only for the work actually in place on the day the titleholder transfers the property to you, and that transfer must happen by day 180. Reg. section 1.1031(k)-1(e) counts a partly built improvement only to the extent it is real property under local law, and any construction after you take title 'will not be treated as the receipt of property of a like kind.' Budget money that was not turned into bricks and soil work by then comes back as boot.
At a glance
| Deadline | Transfer to you by day 180, or earlier if your return is due first |
|---|---|
| What counts | Land plus improvements in place on the transfer date |
| Unfinished work | Counts only to the extent it is real property under local law |
| Work after transfer | Treated as services, not like-kind property |
| Identification | Legal description of the land plus as much construction detail as practicable |
| 200 percent test | Uses the estimated value as of the expected receipt date |
| Unspent budget | Taxable boot up to your realized gain |
The regulation measures the property on the day you receive it, not when the builder finishes
Reg. section 1.1031(k)-1(e)(1) lets you identify replacement property that 'is not in existence or is being produced'. Paragraph (e)(3)(iii) then says real property received before production is complete is treated as substantially the same as identified if it would have been once finished, 'only to the extent the property received constitutes real property under local law.'
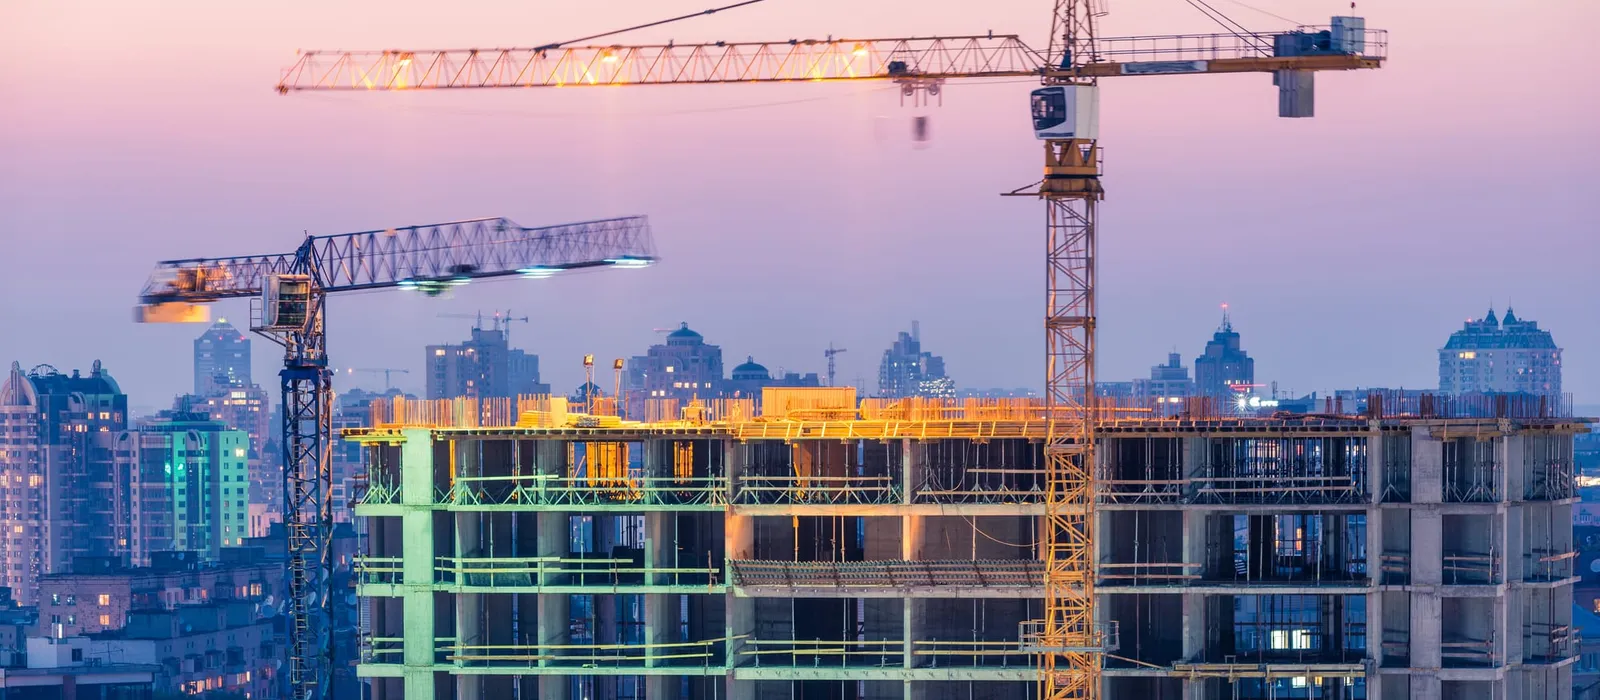
The regulation's own example makes the point with numbers. Property M is transferred when construction is 20 percent complete, and it counts 'to the extent of the underlying land and the 20 percent of the construction that is completed.' The other 80 percent buys nothing for the exchange.
Paragraph (e)(4) closes the last door: a transfer for services, including production services, is outside section 1031, so 'any additional production occurring with respect to the replacement property after the property is received by the taxpayer will not be treated as the receipt of property of a like kind.'
Day 180 is a transfer deadline, set by two clocks at once
The exchange period ends at the earlier of 180 days after your sale or your return due date with extensions, under Reg. section 1.1031(k)-1(b)(2)(ii). If the titleholder acquired the land after your sale, the parking rules of Rev. Proc. 2000-37 add a second limit: the property must leave the arrangement within 180 days of the titleholder taking title.
Whichever date comes first is the day the titleholder must deed the land and improvements to you. The calendar risk in a December sale is real, because an unextended April return date can arrive before day 180; see extending the 45-day and 180-day deadlines.
Construction can continue after that date with your own money. It simply does not count toward the exchange.
Identify the land precisely and describe the improvements as fully as you can
Paragraph (e)(2) says identification of improvements to be constructed is adequate 'if a legal description is provided for the underlying land and as much detail is provided regarding construction of the improvements as is practicable at the time.' Attach the plans, scope or budget you have by day 45.
For the 200 percent rule, a property to be produced is valued at its estimated fair market value 'as of the date it is expected to be received', not its value as raw land. Substantial design changes after day 45 can mean the property you receive is no longer substantially the same as the one you named.
The builder-owned version of the same problem, where you buy new construction directly, is covered in buying new construction as replacement property.
Worked example: $550,000 of work in place on a $800,000 budget
Hypothetical, round numbers; run your own numbers with your CPA. You sell a debt-free rental for $1,200,000 with a $500,000 gain. The titleholder buys a lot for $400,000 and plans an $800,000 building, all funded with your exchange proceeds.
By day 175 contractors have completed and been paid for $550,000 of work, and the titleholder deeds the property to you. Your like-kind property received is $950,000: the lot plus the work in place. The $250,000 not yet spent on completed work is boot.
That $250,000 is taxable because it is smaller than your $500,000 gain. Deposits the titleholder paid for work not yet installed do not help, because paragraph (e)(3)(iii) looks only at what is real property under local law on the transfer date.
Size the scope to the calendar, and fill any gap with property that closes on time
Front-load the work that becomes real property fastest: site work, foundations, framing. Finishes and equipment ordered but not installed are the most common source of boot.
If the schedule will not fit, shrink the improvement scope financed with exchange money and pay for the rest yourself after the transfer. Or name a second replacement on the 45-day list, such as a Delaware Statutory Trust interest, to absorb proceeds the construction cannot use in time (leftover cash after an exchange).
The full structure, including who supervises the contractor, is in the improvement exchange guide, and the planned improvement exchange cost page covers the fees.
Related questions
Can the titleholder keep building after it deeds the property to me?
It can if you pay, but none of that work counts. Reg. section 1.1031(k)-1(e)(4) treats post-receipt production as services, not like-kind property.
Does a certificate of occupancy matter?
Not for the exchange. The test is how much of the improvement is real property under local law on the transfer date, finished or not.
Can I supervise construction myself?
Yes. Rev. Proc. 2000-37 section 4.03 allows you to manage the property, supervise improvement or act as contractor without breaking the safe harbor.
What if materials are delivered to the site but not installed?
Materials that are not yet part of the real property under local law are generally not real property received, so the money spent on them risks being boot.
Can I identify a building I have not designed yet?
Yes, with a legal description of the land and as much detail on the improvements as is practicable by day 45.
Sources
Checked against these publications on September 30, 2026. Rules and figures change; confirm the current version with your CPA or attorney before you act. This page is general information, not tax or legal advice.