The short answer
Warehouses are on the list of buildings in Treas. Reg. Section 1.1031(a)-3, so the structure, land, docks, paving, wiring and HVAC exchange as real property, while racking, cranes, compressors and other equipment designed to be removed do not and are sold on a separate bill of sale. The tax on a sale is unrecaptured section 1250 gain at a maximum 25% on straight-line building depreciation, ordinary income on any 5-, 7- or 15-year cost-segregation items, and 15% or 20% capital gain plus the 3.8% NIIT on the rest. Replacement can be another warehouse, a net-lease industrial building or industrial DSTs that spread one sale across several buildings and markets.
At a glance
| Building status | Warehouses and factories are listed buildings, Reg. Section 1.1031(a)-3 |
|---|---|
| Component test | 4 factors: removal cost, designed to move, removal damage, installed at construction |
| Recapture | Unrecaptured section 1250 gain max 25%; section 1245 cost-seg items at ordinary rates |
| Buy-side equipment | Up to 15% of replacement value stays incidental for the QI safe harbor, but is still boot |
| Depreciation | Nonresidential real property 39 years; land improvements 15 years |
| Reporting | Form 8824; recognized recapture on line 21 (2025 instructions) |
Warehouses are named buildings; racking and cranes are equipment sold outside the exchange
Treas. Reg. Section 1.1031(a)-3 lists warehouses and factories as buildings, and it lists the systems that serve them as structural components: wiring, plumbing, central heating and air conditioning, doors, sprinklers and fire alarms, elevators and floors. Paved yards, fences and outdoor lighting are inherently permanent structures in their own right, so the truck court and the drive aisles are real property too.
Items not on the list are judged by four factors: the time and expense of installing and removing the item, whether it is designed to be moved, the damage removal would cause, and whether it went in during construction. The regulation's Example 5 treats a 12-ton industrial 3D printer installed during construction as real property, Example 6 treats a raised floor that can be lifted out and reused as not real property, and Example 8 separates conventional drywall partitions (real) from modular partitions (not).
Applied to a warehouse, the transformers, switchgear and bus duct that power the building are part of its electrical system, while pallet racking, conveyors, compressors, rail-mounted cranes and forklifts are designed to be removed and belong on a separate bill of sale. The regulation adds that its definitions carry no inference for depreciation or sections 1245 and 1250, so an item can be real property for the exchange and still be recaptured like equipment.
- Typically real property: dock levelers and doors, HVAC, sprinklers, electrical service, slab, paving, fencing, yard lighting
- Typically not: racking, mezzanine shelving built to disassemble, conveyors, cranes, compressors, vehicles
- Judgment calls: a special foundation for a press, walk-in freezer boxes, process piping; run the four factors with your CPA
Three federal tax layers on a warehouse sale, with the arithmetic on a $6,000,000 price
Hypothetically, you bought the building in 2006 for $2,500,000 with $2,000,000 allocated to the structure, took about $1,000,000 of straight-line depreciation over 39 years, and now sell for $6,000,000 with $200,000 of costs. Gain is $4,300,000: $1,000,000 of unrecaptured section 1250 gain at a maximum 25% (Topic 409), $3,300,000 of long-term capital gain at 20% at that income level, and the 3.8% net investment income tax on all of it, about $1,073,000 of federal tax before your state.
If a cost-segregation study moved part of the cost into 5-, 7- or 15-year classes, gain on those items up to their depreciation is ordinary income under section 1245(a)(1). Here is the trap: Section 1245(b)(4) caps the recapture recognized in an exchange at the boot plus the value of non-section 1245 property you receive, and Publication 544 warns that section 1245 recapture may occur when non-section 1245 property is received even if no other gain would be recognized.
In plain terms, unless the replacement contains its own section 1245 components of comparable value, cost-segregation recapture can become taxable in the year of the exchange, so the calculation belongs on your CPA's desk before you sign. Any recapture recognized is reported on line 21 of the 2025 Form 8824.
Office space inside the warehouse is the same nonresidential building; owner occupancy does not disqualify it
A flex building with 20% office and 80% warehouse is one asset for the exchange. Both parts are nonresidential real property, which Publication 946 defines by example as an office building, store or warehouse depreciated over 39 years, so there is no residential-versus-commercial allocation to make.
If your own company occupied the building, it was held for productive use in a trade or business, which qualifies under Reg. Section 1.1031(a)-1(a) exactly as investment use does. The complication arrives only when the business sells with the building; then equipment, inventory and goodwill are allocated under section 1060 and reported on Form 8594 for the assets section 1031 does not reach, per the Form 8594 instructions.
Lease term, tenant credit and functional obsolescence decide who buys and at what price
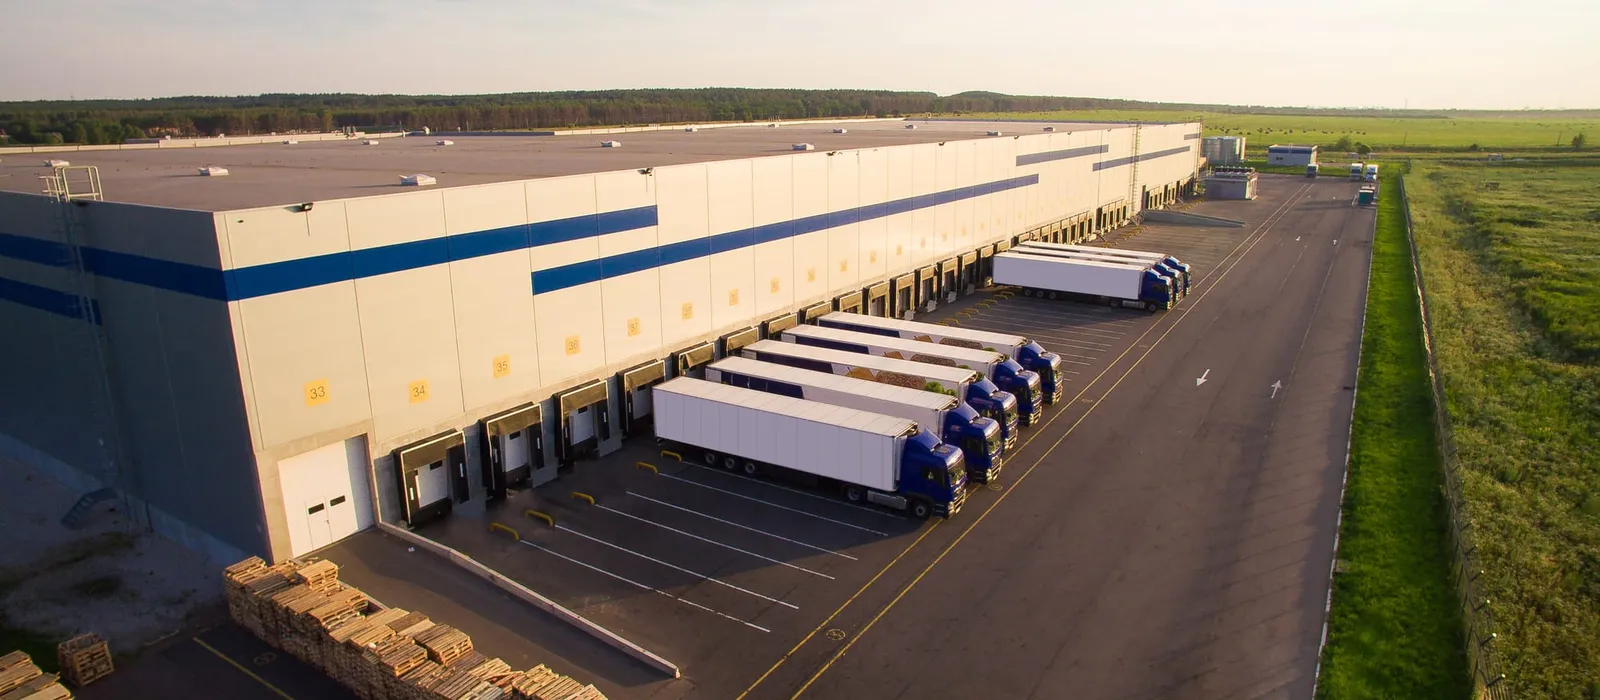
An institutional buyer wants a long lease to a creditworthy tenant in a modern box; an owner-user or value-add buyer wants your older building with a short lease and a price that reflects clear height, dock count, truck-court depth, column spacing and available power. Neither changes the tax analysis, but the buyer type changes your timeline and your certainty of closing, which is what the 45-day clock cares about.
Long-term leases and heavy-power or specialized improvements are not like-kind problems: a leased warehouse is still real property, and improvements you own that are structural components exchange with it. They become valuation questions when a second-generation user would not pay for them.
Hypothetical case: an older local warehouse into two multi-market industrial DSTs
Take the $6,000,000 sale above with a $1,500,000 loan paid off at closing and $200,000 of costs, leaving $4,300,000 of net equity. To defer everything, the replacement must be worth at least $5,800,000 with at least $1,500,000 of debt or extra cash in its place, the balancing rule worked through in the exchange equation guide.
Within 45 days the seller identifies two industrial DSTs, each holding leased distribution buildings in different metros, plus a third as backup under the three-property rule, and closes on both within weeks. Each trust carries its own non-recourse financing that stands in for the retired loan, and the seller ends up with interests in several buildings, tenants and states instead of one aging structure and one lease expiry.
The trade-off is control: under Rev. Rul. 2004-86 the trustee cannot sign new leases except in a tenant bankruptcy or make more than minor non-structural changes, which is why industrial DSTs hold buildings with long leases already in place. What industrial DSTs own and how they fit an exchange is covered on our industrial page and choosing DST asset classes.
What to check in an industrial DST before you put it on the identification list
Read the private placement memorandum for the items below, and have your CPA or attorney check the points that matter to you before the 45th day.
- Tenant roster, lease expirations relative to the projected hold, and rent versus market
- Markets and building specs: clear height, dock ratio, age of roof and HVAC, reserves funded
- Leverage, interest rate and maturity versus the hold period (DST leverage risk)
- Loads and ongoing fees (DST fees and loads) and any master lease (master lease risk)
- Minimum investment and how the trust sizes to your remaining dollars (DST minimums and sizing)
Buying a warehouse as replacement property: tenant credit, clear height and lease term before day 45
Underwrite the tenant before the building. Ask for the tenant's financial statements or a parent guaranty, how long it has occupied the space, whether it has renewed before, and what the lease makes it pay for, because a net lease that leaves roof and structure with the landlord is a different income stream from one that does not. Match the remaining term and any fixed-rent renewal options against the loan maturity you plan to carry, since a lease that expires inside the loan term is the lender's problem first and then yours.
The building's specifications decide who would rent it next. Clear height, dock doors per square foot of floor, truck-court depth, column spacing, floor load and available power set the pool of second-generation users, and a box that works only for the tenant in it should be priced for that risk rather than for the in-place rent. Add the age of the roof and HVAC and a Phase I to the list, and treat heavy-power or process improvements that the tenant installed as items a replacement user may not pay for.
If your relinquished warehouse carried cost-segregation items, the replacement affects what you recognize. Section 1245(b)(4) caps recapture at the boot plus the value of non-section 1245 property received, so a cost-segregation study of the replacement at acquisition, identifying its own section 1245 components, is the record your CPA needs to compute that cap; the sale-side section above explains why the number can be larger than owners expect.
Tenant financials, estoppels and a roof inspection fit inside 45 days if you start them during your sale's escrow. Reg. Section 1.1031(k)-1(c)(4) lets you list three properties of any value, or more if their combined value stays within 200% of your sale, and the list can be rewritten until the identification period closes, so a backup costs nothing. An industrial DST is the fractional route when a direct purchase does not come together, and the DST library covers the offering documents; the checklist section above lists what to read in an industrial trust.
Related questions
Can I sell the racking and equipment to the same buyer without harming the exchange?
Yes. Price them in a separate bill of sale; that portion is a taxable equipment sale with section 1245 ordinary income, and only the real property price goes through the qualified intermediary.
Does the 15% incidental property rule let me exchange into a building with equipment included?
It protects the qualified-intermediary safe harbor when personal property worth up to 15% of the replacement real property comes with the building, but the equipment is still taxable boot; the example in TD 9935 recognizes $100,000 of gain on $100,000 of office furniture acquired with a $1,000,000 building.
Can a warehouse be exchanged for apartments or land?
Yes. Like kind refers to the nature of real property, not its grade or quality, and improved for unimproved real estate is expressly allowed under Reg. Section 1.1031(a)-1(b).
My warehouse sits on a 40-year ground lease. Does that qualify?
A leasehold with 30 years or more remaining is like-kind to a fee, so a 40-year lease qualifies today; the leasehold page covers how options and remaining term are counted.
Is the gain on a cost-segregated warehouse worse than on one depreciated straight-line?
The total gain is the same; the character differs. Accelerated items are ordinary income up to their depreciation, while straight-line building depreciation is unrecaptured section 1250 gain capped at 25%, and only the latter is reliably deferred in a full exchange.
The warehouse I want to buy has three years left on its lease. Is that too short for a replacement property?
Section 1031 sets no minimum lease term; your lender and your re-leasing plan do. Price the building on what a second-generation user would pay for its clear height and loading rather than the in-place rent, ask for the tenant's renewal history and financials before day 45, and name a backup in case the renewal is not signed before you close.
Sources
Checked against these publications on September 30, 2026. Rules and figures change; confirm the current version with your CPA or attorney before you act. This page is general information, not tax or legal advice.
- Treas. Reg. Section 1.1031(a)-3, Definition of real property (Examples 5, 6 and 8)
- TD 9935, Statutory limitations on like-kind exchanges (incidental personal property example)
- IRC section 1245, Gain from dispositions of certain depreciable property
- IRS Publication 544, Sales and Other Dispositions of Assets
- IRS Publication 946, How To Depreciate Property
- Treas. Reg. Section 1.1031(a)-1, Property held for productive use or investment
- Instructions for Form 8594, Asset Acquisition Statement
- Instructions for Form 8824 (2025), Like-Kind Exchanges
- IRS Topic 409, Capital gains and losses
- Rev. Rul. 2004-86, Delaware statutory trusts and section 1031
- Treas. Reg. Section 1.1031(k)-1, Deferred exchanges (identification rules)