The short answer
A warehouse or industrial building that you rent out or use in your business is exchangeable real property, so you can defer the federal gain by selling through a qualified intermediary and buying replacement real estate of equal or greater value within 180 days. What sets the industrial seller apart is the paperwork around the building: which entity is on the deed, how the price splits between the structure and the racking, cranes and business assets, and how long an industrial buyer's environmental review and loan approval take. Owners who want to stop managing dock doors and roofs usually move the proceeds into a traditional DST that spreads the money across several properties, sometimes with part of it in a financed trust to replace the loan being paid off.
At a glance
| Warehouses are named | Reg. section 1.1031(a)-3 lists factories and warehouses among buildings that are real property |
|---|---|
| Equipment | Items designed to be moved, such as most racking and production machinery, sell outside the exchange |
| Owner-occupied | A building your own company uses is held for productive use in a business and qualifies |
| Who exchanges | The owner on the deed for tax purposes; a corporation's building is the corporation's exchange |
| Buyer's Phase I | 40 CFR 312.20: all appropriate inquiries within one year before purchase, some parts within 180 days |
| SBA buyers | 13 CFR 120.131: a borrower buying an existing building must occupy at least 51 percent of it |
| Tax deferred | Up to 25% on depreciation taken, 15% or 20% on the rest, plus 3.8% NIIT where it applies |
| DST minimums | The firm's traditional DST page lists $100,000 to $250,000 per trust |
Industrial sellers come in two kinds, and both can exchange
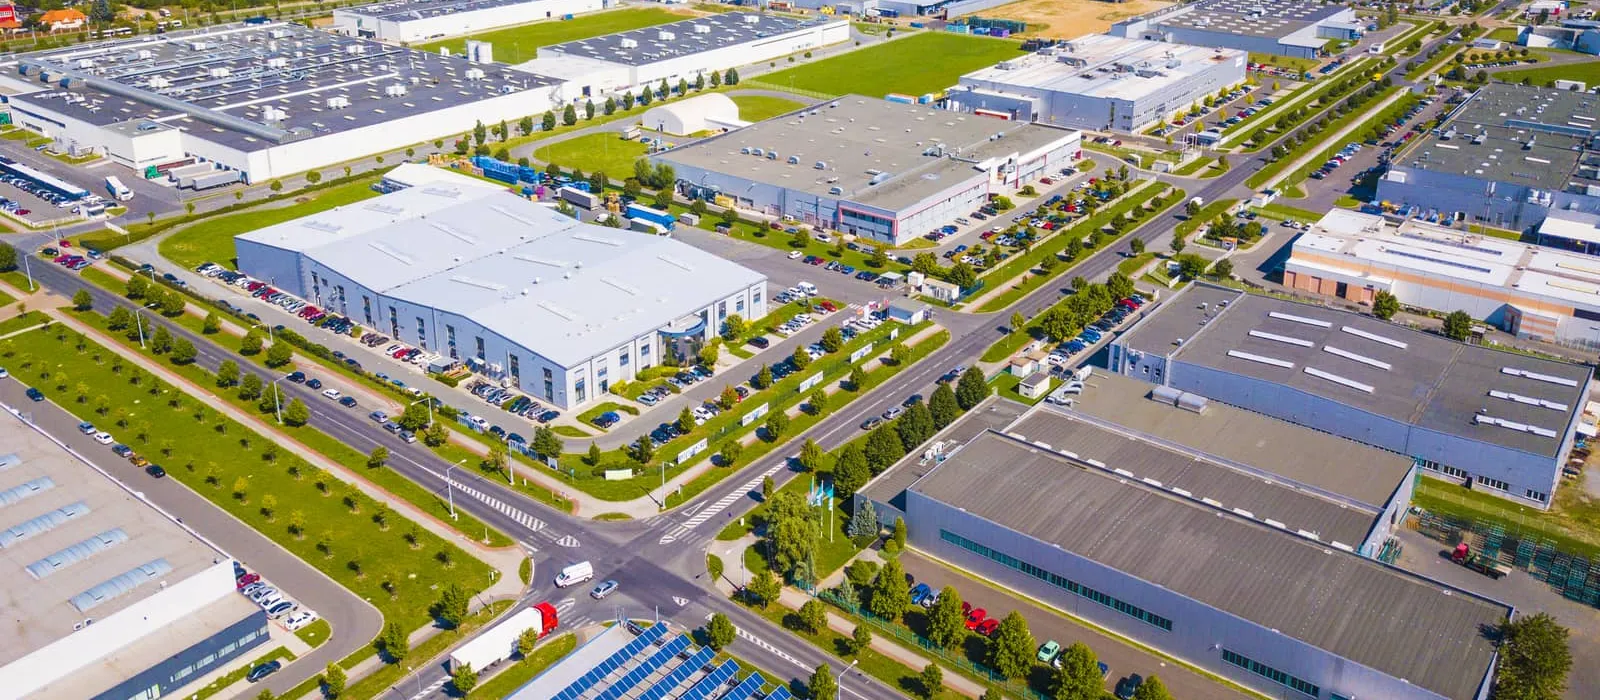
Most warehouse sales fall into one of two stories. A landlord owns a building leased to a distributor, a contractor or a light manufacturer, and is weighing a sale against the next roof, the next lease rollover and the next round of dock and parking lot repairs. An owner-user runs a company out of the building and is selling because the company is being sold, is moving to a bigger site, or is winding down.
Both owners hold the building for a purpose the statute covers. Section 1031(a)(1) defers gain on real property held for productive use in a trade or business or for investment, when it is exchanged for like-kind real property to be held the same way. Using the building in your own business is productive use, so an owner-user does not need a tenant to qualify. What has to change hands is real estate for real estate, and the replacement does not have to be industrial: an apartment trust, a medical office or a mix of several properties all qualify.
The asset-level tax mechanics of a warehouse, from cost segregation to the three federal rates, are worked through on the industrial warehouse property page. This page is about the seller's decisions: who exchanges, what is carved out, how the buyer's timeline fits yours, and where the money goes.
If your company occupies the building, the name on the deed decides who can exchange
Owner-users hold industrial buildings in one of a few ways, and each produces a different taxpayer. If you own the building personally or through a single-member LLC and lease it to your operating company, you are the taxpayer, and you can exchange the building while the company does whatever it is doing with the business. If the building sits inside the operating company itself, a corporation or a multi-member LLC, then that entity is the seller and only that entity can exchange, so the replacement property ends up inside the company too.
That second case catches owners who are selling the business along with the building. The exchange proceeds cannot be paid out to the shareholders and still be deferred; the same-taxpayer rule requires the entity that sold to buy. If you plan to dissolve the company after the sale, that plan and the exchange pull in opposite directions, and the restructuring has to be worked out with your CPA before a buyer is under contract.
When the business and the building are sold together, section 1060 requires the price to be allocated among the assets, and a written allocation the buyer and seller agree to binds both of them. Only the share allocated to the land and building can go through the intermediary; goodwill, inventory and equipment are taxed under their own rules, which our business sale gains page covers. If the company will stay in the building as a tenant after the sale, read the sale-leaseback guide before you set the rent, because the lease terms move the price.
Racking, cranes and machinery: what is real property in an industrial sale
Reg. section 1.1031(a)-3 lists factories and warehouses among the buildings that are real property, along with their structural components. Items that are not listed are tested one by one for whether they are inherently permanent, looking at how they are attached, how hard they are to remove and whether they are designed to stay. The regulation's own examples make the line concrete: a heavy industrial machine installed during construction that would damage the building if removed was treated as real property, while raised flooring installed for it, designed to be moved and reused, was not.
For a typical warehouse sale that means the shell, the slab, the dock levelers built into the structure, the fire sprinklers and the building's electrical and HVAC go through the exchange, while pallet racking, forklifts, conveyors and most production equipment are personal property sold outside it. Put that split in the purchase agreement with a separate bill of sale for the equipment. The equipment's share of the price is taxed in the year of sale, and to the extent you depreciated it the gain is ordinary income under section 1245.
A cost segregation study on the building raises a second question. Components the study moved into five-, seven- or fifteen-year classes were depreciated faster, and section 1245(b)(4) can bring back ordinary income inside an exchange when the replacement carries less section 1245 property than you gave up. Hand the study to your CPA before you sign, so the recapture is known before the replacement is chosen.
An industrial buyer's environmental review and loan approval set your closing date
Industrial buyers almost always commission a Phase I environmental site assessment, because the federal standard for all appropriate inquiries is what lets a buyer claim protection from cleanup liability. Under 40 CFR 312.20 those inquiries must be completed within one year before the purchase, and several parts must be done or updated within 180 days of it. A Phase I that flags a past use, an old tank or a neighbouring site can lead to a Phase II with soil or groundwater sampling, and that can add weeks to the contract.
Owner-user buyers often finance with an SBA loan, and 13 CFR 120.131 requires a borrower buying an existing building to occupy at least 51 percent of it. That means an SBA buyer's approval, appraisal and occupancy plan drive the closing date, and our SBA loan property guide explains what that loan does on your side of the trade.
None of this delay hurts your exchange by itself, because your 45 days do not start until the deed transfers. What hurts is a closing that arrives before your intermediary is engaged or before you have any idea what you will buy, or a closing that slides into late autumn, where the return due date can cut the 180-day period short. Engage the intermediary when the buyer's due diligence period opens, and if you are already under contract without one, our page on setting up the exchange before closing lists what to do this week.
If the buyer asks for part of the price to be held back for environmental work, settle in the contract where a released holdback goes. Money released to you is taxable boot; money that goes to the intermediary inside the exchange period can still be reinvested.
Worked model: a $4,000,000 warehouse with a $1,200,000 loan
Every figure here is hypothetical and rounded. You bought a warehouse years ago for $1,800,000, of which $1,400,000 was building, and have taken about $600,000 of straight-line depreciation, so your adjusted basis is $1,200,000. A buyer pays $4,000,000, selling costs are $200,000, and a $1,200,000 loan is paid off at closing. Racking you own is sold to the same buyer for $100,000 on a separate bill of sale, outside the $4,000,000.
Without an exchange, the gain on the building and land is $2,600,000. Up to $600,000 of it is unrecaptured section 1250 gain taxed at a maximum 25 percent under section 1(h), or $150,000; the remaining $2,000,000 at 20 percent is $400,000; and if the 3.8 percent tax in section 1411 applies to you, it adds about $98,800. That is close to $650,000 of federal tax before your state takes its share.
To defer all of it, the replacement has to cost at least $3,800,000, and the $1,200,000 loan paid off has to be matched by new debt in the replacement or by cash you add, because Reg. section 1.1031(d)-2 treats debt relieved as money received. The $2,600,000 of equity reaching the intermediary is what you invest. Your CPA should rerun this with your real depreciation schedule and state before any of it is relied on.
- Exchangeable: $4,000,000 of land, building and built-in components.
- Outside the exchange: $100,000 of racking, taxed this year as ordinary income to the extent depreciated.
- Value to replace: $3,800,000. Equity to reinvest: $2,600,000. Debt to replace: $1,200,000.
Where industrial proceeds usually go when the owner is done managing a building
An owner leaving industrial real estate tends to want three things: income without a roof or a tenant to manage, the debt replaced without signing a personal guarantee, and not all of the money riding on one building. A traditional Delaware Statutory Trust answers the first and third: the trust owns stabilized property with management, leases and financing already in place, and the firm's traditional DST page lists industrial among the sectors offered, with minimums between $100,000 and $250,000 per trust. A $2,600,000 exchange can be spread across several trusts, sectors and regions instead of one building.
The debt is solved by choosing trusts that already carry non-recourse loans, so your share of the trust's debt replaces the loan you paid off, or by putting a small allocation into a highly leveraged structure. The cash out DST is the firm's zero cash flow version: it is built on long-term net leases and non-recourse debt, operating income services the loan, and there are no current distributions. The financed replacement versus all-cash DST guide compares the two approaches.
A DST interest is a security sold to accredited investors in a private placement, and it carries real risks: there is no public market for it, the sponsor decides when the property is sold, distributions can be reduced or stop, and you can lose principal if a tenant fails or values fall. Under Rev. Rul. 2004-86, the ruling that lets a DST interest count as real property, the trustee in the ruled facts could not take new capital, refinance or renegotiate the lease, which is part of why these trusts suit income seekers rather than owners who want to steer the property.
If your building has a single tenant whose lease is running out, the sale timing questions on our NNN lease expiration page apply to you as well. And if you would rather own another whole building, the net-lease underwriting page sets out what to check before day 45.
What to send us before the buyer's due diligence period ends
A proposal for an industrial seller is built from a short list. Send the purchase agreement or letter of intent with the expected closing date, the loan payoff figure, your depreciation schedule and any cost segregation study, the name of the entity on the deed, the state the building is in and the state you live in, whether your company will stay as a tenant, and how much income you want from the replacement. The free proposal uses those figures to show the gain at stake, the value and debt to replace, and the structures that fit.
If you would rather talk it through first, book a free consultation. The sooner we see the contract, the more of the 45 days you keep for choosing rather than scrambling.
Related questions
My operating company leases the building from my LLC. Can the LLC exchange it?
Yes. The LLC holds the building to rent to the company, which is productive use, and if it is a single-member LLC you are the taxpayer for the exchange. The operating company's own sale or continuation does not change that, but the replacement must be bought by the same owner that sold.
Should the business and the building be sold in one contract?
They can be, but the price must be allocated among the assets under section 1060, and only the land and building share can be exchanged. Separate contracts or a clear written allocation make the exchangeable amount easy for your intermediary and CPA to see.
The buyer's Phase I found something. Does that affect my exchange?
Not directly; it affects the closing date and possibly the price. Watch any holdback: if cleanup money held back from the price is later released to you, it is taxable boot unless it goes to your intermediary inside the exchange period.
Does a cost segregation study make the exchange worse?
It can add ordinary income. Components depreciated as section 1245 property can be recaptured in an exchange when the replacement holds less of that kind of property, so your CPA should map the study against the replacement before you identify it.
Can I exchange only part of the proceeds and keep some cash?
Yes. Cash you keep is taxed as boot up to the amount of your gain, and the rest stays deferred. In the hypothetical above, keeping $300,000 would make $300,000 taxable while the remaining gain is deferred.
Do I have to buy another industrial property?
No. Any US real property held for business or investment is like kind, so a warehouse can become apartment, medical or retail property, or interests in trusts that own them.
Sources
Checked against these publications on November 8, 2026. Rules and figures change; confirm the current version with your CPA or attorney before you act. This page is general information, not tax or legal advice.
- 26 U.S.C. section 1031, Exchange of real property held for productive use or investment
- Treas. Reg. section 1.1031(a)-3, Definition of real property
- Treas. Reg. section 1.1031(d)-2, Treatment of assumption of liabilities
- 26 U.S.C. section 1060, Special allocation rules for certain asset acquisitions
- 26 U.S.C. section 1245, Gain from dispositions of certain depreciable property
- 26 U.S.C. section 1(h), Maximum capital gains rate
- 26 U.S.C. section 1411, Net investment income tax
- 40 CFR 312.20, All appropriate inquiries (timing of inquiries before acquisition)
- 13 CFR 120.131, SBA occupancy requirements for existing buildings and new construction
- IRS, Rev. Rul. 2004-86, Delaware statutory trust interests as replacement property